CONTACT
  • Login
Upgrade
LONDONwebzine
Advertisement
  • Home
    • Our Authors
    • Media Kit
    • Contact
    • Cookie Policy
    • Terms and Conditions
  • News
  • Business
  • Lifestyle
    • Beauty
    • Kids
    • Gastronomy
    • Sustainable living
    • Well-being
    • Creativity
  • Culture
  • Sports
  • Travel
  • Global London
  • Insights
  • Local Guide
    • Activities in London
    • Hotels in London
    • Nightlife in London
    • Restaurants in London
    • Services in London
    • Shopping in London
No Result
View All Result
LONDONwebzine
No Result
View All Result
Home Business

How to Buy Your First Buy-to-Let Flat in London

Everything you need to know before you buy your first rental flat in London, from mortgages to the latest landlord rules.

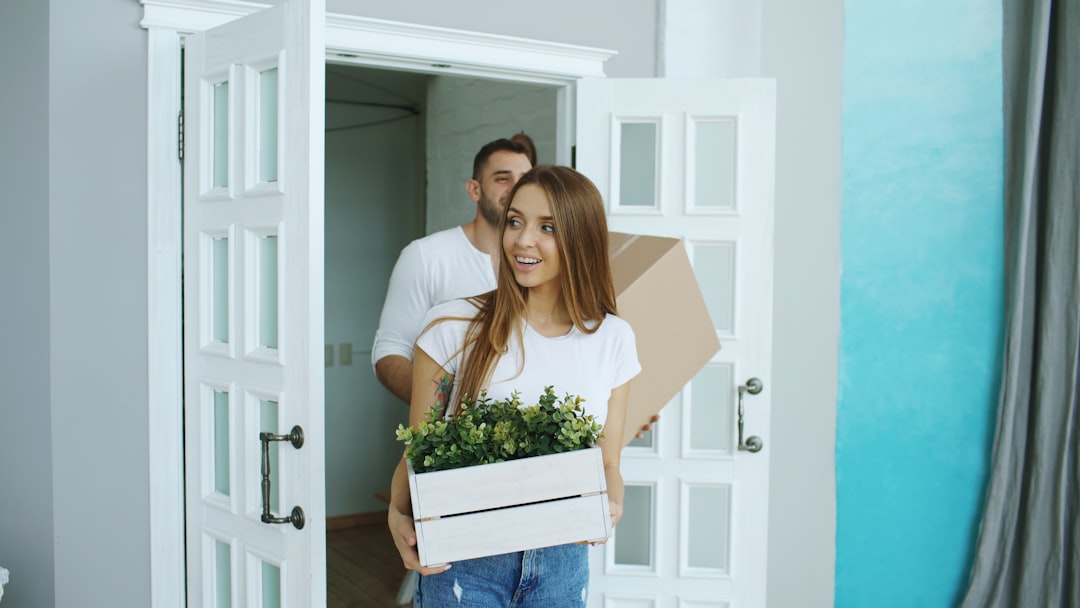
A couple visiting a residential property with an estate agent, discussing the space during a buy-to-let flat viewing in Londo

Buy-to-let investment in London demands more preparation today than at any point in the past decade, new taxes, new tenancy laws, and tighter mortgage conditions mean that informed buyers gain a clear edge over those who act on instinct alone.

What a buy-to-let mortgage actually means

A buy-to-let mortgage is specifically designed for landlords who buy one or more properties as an investment, because you cannot use a standard residential mortgage to finance a property you intend to rent out. That distinction matters from day one of your planning.

Most buy-to-let mortgages are interest-only. This means your monthly payments cover only the interest on the loan, not the capital you borrowed. You must repay the full capital at the end of the mortgage term. Many landlords plan to sell the property at that point, ideally at a profit.

Most lenders expect a minimum personal income of £25,000 alongside rental income that covers at least 125% of mortgage payments. Deposit requirements typically range from 25% to 40% of the property value. A larger deposit gives you access to better rates and stronger lender confidence.
How mortgage rates affect your buy-to-let returns

The average interest rate across all new buy-to-let loans in the UK was 4.77% in Q4 2025. That figure is a useful benchmark, but your personal rate will depend on your deposit size, credit profile, and the property type.

The loan-to-value ratio is the primary factor that determines your buy-to-let mortgage interest rate. This percentage represents your mortgage amount relative to the total value of the property. The vast majority of new buy-to-let loans carry LTV ratios below 75%. Therefore, a larger deposit reduces your rate directly.

Fixed-rate mortgages are particularly useful during periods of economic uncertainty, because they protect landlords from sudden interest rate increases. They make it easier to plan cash flow, forecast expenses, and manage rental income. For a first-time landlord, that predictability has real value.

Buy-to-let stamp duty costs in London

If you buy an additional residential property such as a buy-to-let, you must pay a 5% surcharge on top of standard Stamp Duty Land Tax rates across every band. This surcharge increased from 3% to 5% on 31 October 2024.
On a £400,000 property in London, you pay 0% plus the 5% surcharge on the first £125,000, 7% on the next £125,000, and 10% on the remaining £150,000, giving a total stamp duty bill of £30,000. Factor this into your budget before you make an offer.

If you are an investor, you must ensure that higher acquisition costs and the 5% additional property surcharge have been factored into your projected returns. Ignoring this cost is one of the most common errors first-time landlords make in London.
A couple discussing buy-to-let mortgage options with a broker in a London financial office

Expert perspective on the London rental market

The London private rental sector continues to attract serious capital, but the environment for new landlords has changed structurally. Stamp duty surcharges, tighter mortgage stress tests, and new tenancy legislation all compress margins at the entry level. Investors who focus on gross yield alone miss the full picture. The most resilient buy-to-let portfolios in London today are built around net yield calculations that account for void periods, management fees, maintenance, and rising compliance costs. Properties with strong energy performance credentials are also increasingly preferred by lenders and tenants alike, and that preference will only grow as EPC requirements tighten. First-time investors should treat the purchase as a business decision from day one, not a passive savings product.

Industry perspective, property finance and investment professionals in London

Rental yields and what to expect

The average gross buy-to-let rental yield for the UK in Q4 2025 was 7.18%, compared with 6.99% in the same quarter of the previous year. London yields vary significantly by borough, with outer zones consistently outperforming central areas on a percentage basis.
You might also like

A focused investor reviews a legal pack before participating in commercial auctions in London

Commercial auctions: what London buyers must know

18/09/2026
A startup founder presents to investors during an autumn accelerator demo day in London

Autumn accelerator: London startup Q4 guide

13/09/2026
A London finance director conducts a business audit at her office desk in the City, reviewing financial records before Q4.

Business audit: why September is critical

01/09/2026
A founder at a London office desk refines materials for a London accelerator application

London accelerator deadlines: sharpen your pitch

31/08/2026
An experienced business mentor in London reviews a startup plan with a young founder at a desk

Business mentor London: find the right one

13/08/2026
A business owner carefully reviewing a commercial lease agreement in a bright London studio space

Commercial lease tips for London studios

07/08/2026

Becoming a landlord can still be an attractive option, even with higher interest rates and more rental regulations. Renting out a property can generate a steady monthly income, while the property itself could grow in value over time. Both income and capital appreciation matter to a long-term investor.

Always calculate net yield, not gross yield. Deduct mortgage payments, service charges, letting agent fees, maintenance, insurance, and void periods from your rental income before you assess whether a flat produces a genuine return.
A property investor inspecting a buy-to-let flat in London before signing the rental agreement

The Renters’ Rights Act: what every new landlord must know

The Renters’ Rights Act 2025 received Royal Assent on 27 October 2025. It represents the largest reform of the private rented sector in 40 years. Every new landlord in London must understand its core provisions before completion.

From 1 May 2026, any assured shorthold tenancy automatically became a rolling periodic tenancy. You can no longer agree a fixed rental term with a tenant or create a tenancy with an end date. The tenancy continues until either party ends it. You cannot evict a tenant without giving a legally valid reason.

Under the Renters’ Rights Act 2025, landlords can only increase rent once per year, by serving a Section 13 notice. This notice must set out the proposed new rent, reflect the current market rate, and give tenants at least 2 months’ notice before the increase takes effect. Compliance with this process is not optional.

Your buy-to-let flat: final steps before you invest

Every successful buy-to-let purchase in London starts with a precise financial model, not an approximate one. Calculate your full stamp duty cost, your net yield after all expenses, and your mortgage affordability under current stress-test conditions before you exchange contracts.

A buy-to-let flat in the capital can still deliver strong returns, but the margin for error is smaller than it was 5 years ago. Engage a specialist mortgage broker, a tax adviser, and a letting agent with local knowledge before you commit. More than 59,000 buy-to-let loans were advanced in the UK in the final quarter of 2025, 18.2% more than the same period in the previous year, which confirms that serious investors continue to enter this market, but they do so with proper preparation. Treat your buy-to-let as the business it is, and London will reward that discipline.
Discover more about buy-to-let

  • Stamp Duty Land Tax: residential property rates (GOV.UK)
  • Buy-to-Let Lending Data and Yields, Q4 2025 (UK Finance)
  • The Renters’ Rights Act 2025: a guide for private landlords in England (Pinsent Masons)
Previous Post

FTSE 100 slides as oil and rate fears bite

Next Post

London property still rewards patient investors

Related Posts

A focused investor reviews a legal pack before participating in commercial auctions in London
Business

Commercial auctions: what London buyers must know

18/09/2026
A startup founder presents to investors during an autumn accelerator demo day in London
Business

Autumn accelerator: London startup Q4 guide

13/09/2026
A London finance director conducts a business audit at her office desk in the City, reviewing financial records before Q4.
Business

Business audit: why September is critical

01/09/2026
A founder at a London office desk refines materials for a London accelerator application
Business

London accelerator deadlines: sharpen your pitch

31/08/2026
An experienced business mentor in London reviews a startup plan with a young founder at a desk
Business

Business mentor London: find the right one

13/08/2026
Next Post
A property investor reviews documents at a desk, making decisions about London property in a modern office setting

London property still rewards patient investors

Leave a Reply Cancel reply

Your email address will not be published. Required fields are marked *

No Result
View All Result

Our Focus

LONDONwebzine is your international window on London: lifestyle, business, culture, sports and events for a global audience drawn to the capital's endlessly dynamic scene.

Our Readers

LONDONwebzine addresses readers who engage with London at a high level: professionally, financially, strategically, and as decision-makers in their fields.

Our Approach

Lifestyle, culture, and innovation are integrated as context and indicators of economic influence, creative leadership, and global soft power, not standalone entertainment.

Recent Post

  • Cold plunge in Hackney: a first-timer’s guide
  • Ethiopian restaurants London: best picks

© 2026 LONDONwebzine by NOOR & NOOR — part of WEBZINE.world.

Welcome Back!

Login to your account below

Forgotten Password?

Retrieve your password

Please enter your username or email address to reset your password.

Log In
Manage Consent
To provide the best experiences, we use technologies like cookies to store and/or access device information. Consenting to these technologies will allow us to process data such as browsing behavior or unique IDs on this site. Not consenting or withdrawing consent, may adversely affect certain features and functions.
Functional Always active
The technical storage or access is strictly necessary for the legitimate purpose of enabling the use of a specific service explicitly requested by the subscriber or user, or for the sole purpose of carrying out the transmission of a communication over an electronic communications network.
Preferences
The technical storage or access is necessary for the legitimate purpose of storing preferences that are not requested by the subscriber or user.
Statistics
The technical storage or access that is used exclusively for statistical purposes. The technical storage or access that is used exclusively for anonymous statistical purposes. Without a subpoena, voluntary compliance on the part of your Internet Service Provider, or additional records from a third party, information stored or retrieved for this purpose alone cannot usually be used to identify you.
Marketing
The technical storage or access is required to create user profiles to send advertising, or to track the user on a website or across several websites for similar marketing purposes.
  • Manage options
  • Manage services
  • Manage {vendor_count} vendors
  • Read more about these purposes
View preferences
  • {title}
  • {title}
  • {title}
No Result
View All Result
  • Home
    • Our Authors
    • Media Kit
    • Contact
    • Cookie Policy
    • Terms and Conditions
  • News
  • Business
  • Lifestyle
    • Beauty
    • Kids
    • Gastronomy
    • Sustainable living
    • Well-being
    • Creativity
  • Culture
  • Sports
  • Travel
  • Global London
  • Insights
  • Local Guide
    • Activities in London
    • Hotels in London
    • Nightlife in London
    • Restaurants in London
    • Services in London
    • Shopping in London

© 2026 LONDONwebzine by NOOR & NOOR — part of WEBZINE.world.

Are you sure want to unlock this post?
Unlock left : 0
Are you sure want to cancel subscription?
Verified by MonsterInsights
enEnglishfrFrançais